How a SWFL Recession Changes Your Home Purchase
Changing home prices, insurance costs, interest rates, and job security can make any purchase feel uncertain. Buying a home during a recession in SWFL isn’t automatically a bad decision, but it does require a clear-eyed plan.
We recommend weighing your finances, local conditions, property risks, and long-term plans before you focus on headlines. A careful process can show whether a home fits your life and budget.
Key Takeaways
- A recession can create negotiating room, but personal financial stability matters more than market predictions.
- Compare Fort Myers, Cape Coral, Naples, Bonita Springs, and Estero at the neighborhood level.
- Include insurance, flood coverage, HOA fees, maintenance, and assessments in your monthly budget.
- Protect your offer with inspections, insurance quotes, and realistic contingencies.
- Choose a home you can afford to keep for several years.
Buying a Home During a Recession in SWFL: Is It the Right Move?
The right choice depends on your income, savings, debt, and timeline. A recession may bring fewer competing buyers, price reductions, seller credits, or more flexible closing dates. However, none of those possibilities make an unaffordable home safe to buy.
A downturn can also bring tighter lending, lower values, higher insurance premiums, and costly repairs after storms. Short-term investors face more exposure if they need to sell quickly. Buyers who expect to stay for several years usually have more time to ride out market changes.
How Southwest Florida’s Market Can Differ From the National Economy
SWFL doesn’t move as one market. Seasonal demand, retirees, second-home buyers, migration, tourism, new construction, waterfront demand, and hurricane recovery can affect different areas in different ways.
Compare recent sales, active inventory, days on market, and price reductions in Fort Myers, Cape Coral, Naples, Bonita Springs, and Estero. A local agent can also help you separate a broad recession headline from a neighborhood’s actual conditions. Our Southwest Florida real estate market timing guide can help you frame those local questions.
When Waiting May Be Safer Than Buying
Waiting may be the wiser choice if your income is unstable, your emergency fund is thin, or consumer debt already strains your monthly cash flow. The same applies when insurance quotes exceed your comfort level or you expect to move within a few years.
A lower purchase price may not offset property taxes, flood coverage, maintenance, closing costs, or rising HOA fees. We would rather see you wait than stretch into a home that leaves no room for ordinary setbacks.
Build a Recession-Ready Home-Buying Budget
Start with the full monthly cost, not the principal and interest payment shown in a loan estimate. Add property taxes, homeowners insurance, flood insurance when needed, HOA or condo fees, utilities, routine maintenance, and possible special assessments.
Keep several months of living expenses in reserve after closing. Also, review your credit, compare loan programs, and get preapproved before house hunting. Your lender’s maximum approval isn’t a spending target. It is only one data point.
Our guidance on how credit affects home buying can help you understand why loan options and monthly costs may differ between buyers.
Account for SWFL Insurance, Flood, and Storm Costs
Insurance can change a property’s affordability quickly in coastal and inland SWFL. Before making an offer, review flood zones, elevation information, roof age, wind mitigation features, hurricane shutters, generators, seawalls, drainage, and prior storm damage.
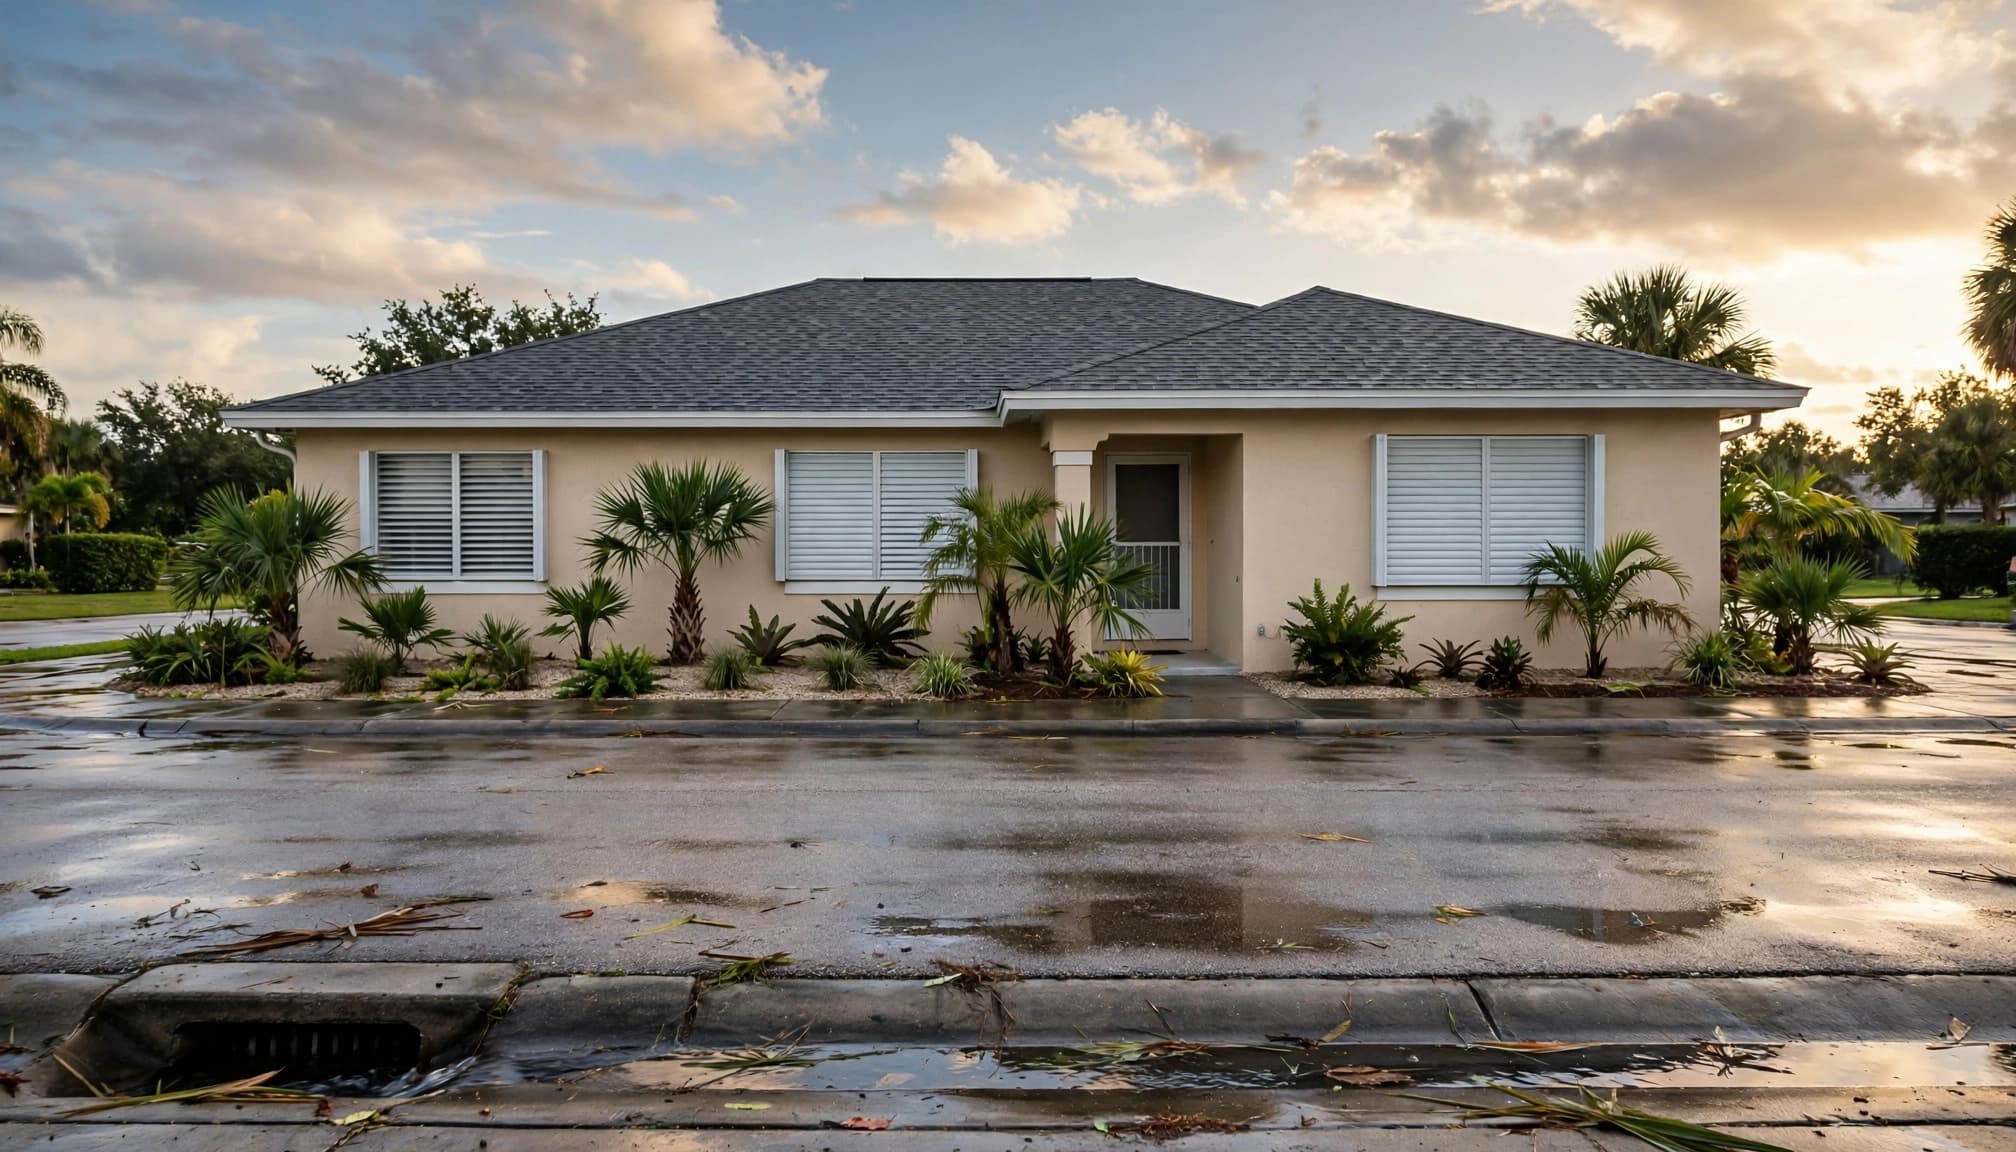
Flood coverage may be required as a mortgage condition depending on the home’s location, according to the Florida Office of Insurance Regulation’s flood-insurance guidance. Get written insurance quotes during due diligence, not after contingencies expire.
A house that fits the mortgage payment can still miss the budget once wind, flood, roof, and assessment costs enter the picture.
Condo buyers should examine the association’s reserves, master insurance policy, recent repairs, and pending assessments.
Compare Loan Options Without Chasing the Lowest Rate
Fixed-rate, adjustable-rate, FHA, VA, and conventional loans each create different monthly and long-term tradeoffs. Compare points, lender fees, mortgage insurance, rate-lock terms, and projected payments alongside the advertised rate.
Ask several lenders how each option holds up if income changes or home values decline. Also ask how much cash you will retain after closing. Fannie Mae’s flood-insurance requirements show why lender requirements can affect the final cost of a specific property.
Negotiate Wisely and Protect the Purchase
A strong recession-era offer is careful, not reckless. Use recent comparable sales, seller motivation, inspection findings, and appraisal risk to support your price and terms. Seller credits, closing-cost help, repair credits, and rate buydowns may be worth discussing when the numbers support them.
Don’t waive inspections because a property looks discounted. Access Jack Real Estate can help you interpret local data and coordinate conversations with qualified lenders, inspectors, insurance agents, and title professionals.
A Practical Due Diligence Checklist for SWFL Buyers
After an offer is accepted, complete these checks before your deadlines:
- Order a general inspection and review the roof, plumbing, electrical system, HVAC, and major appliances.
- Obtain insurance quotes and confirm any flood requirements before removing contingencies.
- Review permits, storm repairs, property taxes, HOA or condo documents, and pending assessments.
- Complete the appraisal and final walkthrough before closing.
- For waterfront homes, inspect seawalls, docks, drainage, and signs of erosion.
Our home buying process explained offers more context for keeping these steps in the right order.
Mistakes That Can Turn a Discount Into a Loss
Buyers can get hurt by assuming prices cannot fall further or by trusting an online estimate over an inspection and local comparable sales. Others use every available dollar for the down payment, ignore insurance availability, or focus only on the interest rate.
Judge each home by its total cost, condition, location, and usefulness over time. A modest house with stable carrying costs often makes more sense than a larger property that strains your monthly budget.
A Comfortable Purchase Matters More Than Perfect Timing
Buying during a recession in SWFL can work when you have stable finances, cash reserves, realistic long-term plans, and a firm grasp of insurance and storm-related costs. Affordability matters more than trying to predict the exact bottom of the market.
Review local data and your personal situation with Access Jack Real Estate and qualified lending, insurance, and inspection professionals. The right home is one you can keep comfortably through uncertain conditions.